Farm Insurance · Windsor-Essex
Farm Insurance
Farm insurance packages address working agricultural property in Essex County — barns, machinery, farm liability, and livestock — where purchased and subject to causes of loss, limits, and endorsements on your policy. That is different from a standard homeowner policy for a rural residence, from greenhouse and controlled-environment agribusiness on a separate route, and from Agricorp Production Insurance or other government AgriInsurance programs for crop yield loss. Licensed trucks and passenger vehicles used on public roads still require Ontario automobile insurance. Premium Insurance Brokers can help family and commercial farms compare private farm property and liability programs for how you actually farm.
For Windsor–Essex working farms — family, mixed, crop, and livestock operations — reviewed through an independent broker who can coordinate farm property, liability, machinery, and livestock coverage without duplicating greenhouse agribusiness or government crop programs.
What's covered
Farm insurance is organized here by farm property and buildings, machinery and equipment, farm liability, and livestock — because each insuring agreement uses different perils, schedules, and limits on most Ontario farm packages.
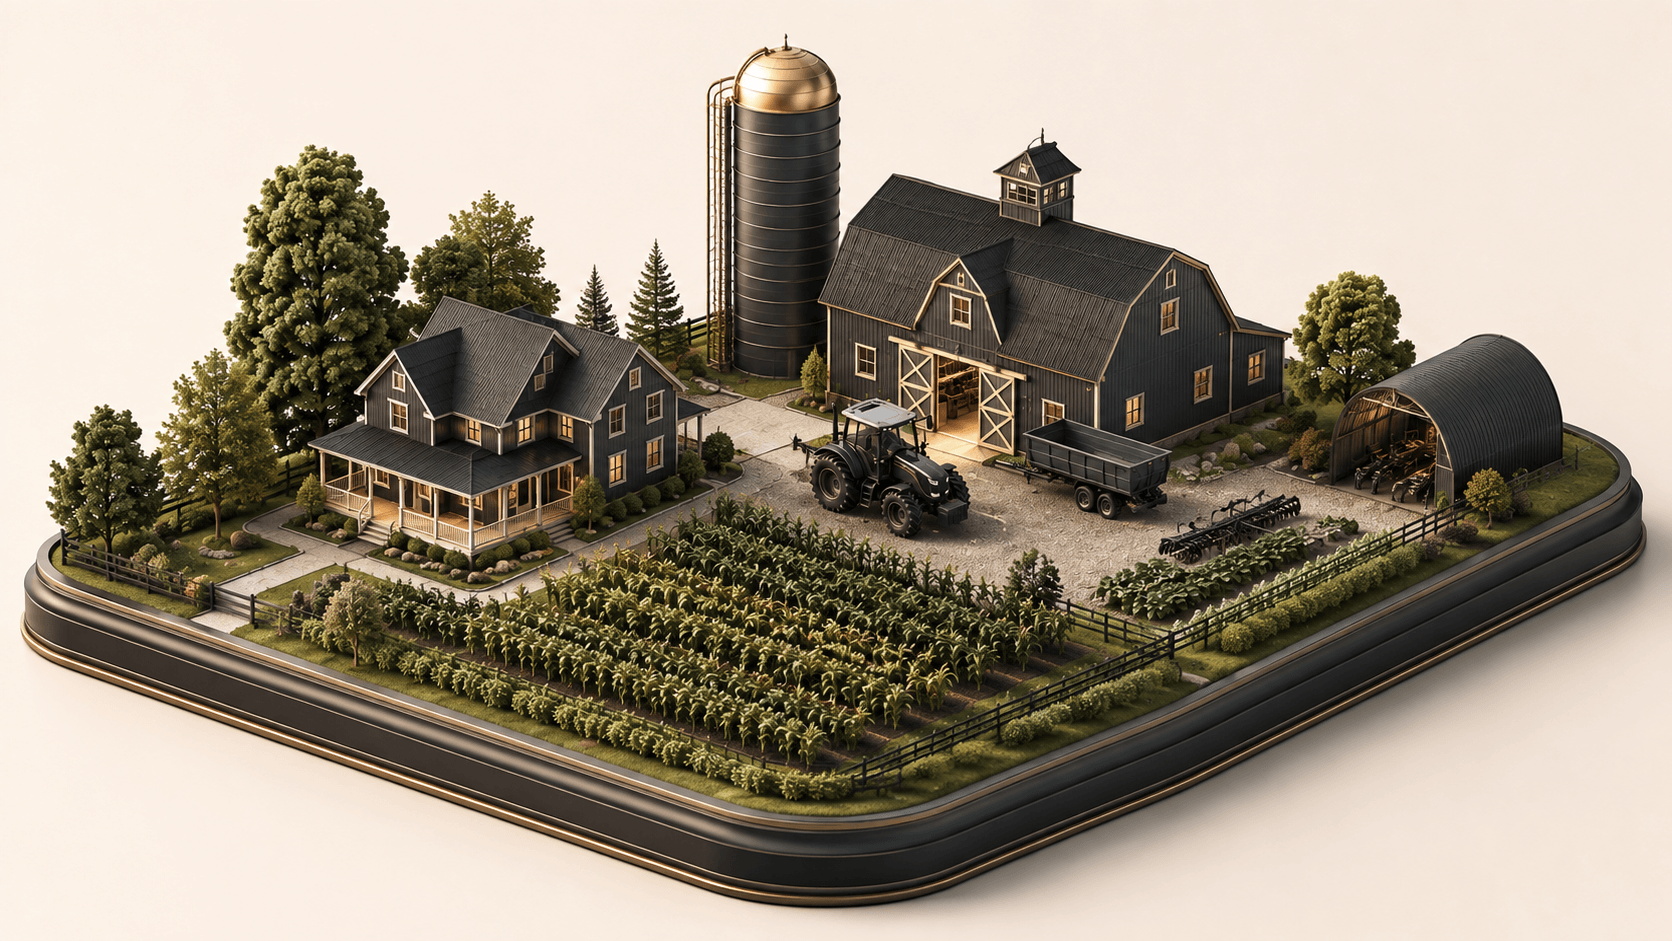
Barns and outbuildings are farm assets — not ordinary home attachments: Working farms carry values in barns, machine sheds, grain storage, and fencing that exceed what a typical homeowner policy contemplates. Farm property sections schedule structures and may use different peril packages for dwellings versus outbuildings. Vacant barns, seasonal occupancy, and wood-frame construction affect underwriting. Accurate building values support proper limits after expansions or new construction — underinsurance reduces partial-loss payments on many forms.
Barns and outbuildings are farm assets — not ordinary home attachments
Working farms carry values in barns, machine sheds, grain storage, and fencing that exceed what a typical homeowner policy contemplates. Farm property sections schedule structures and may use different peril packages for dwellings versus outbuildings. Vacant barns, seasonal occupancy, and wood-frame construction affect underwriting. Accurate building values support proper limits after expansions or new construction — underinsurance reduces partial-loss payments on many forms.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
Greenhouse operations, farm trucks, and broader commercial coverage may need separate routes — explore related products from Premium.
Farm insurance FAQ
Straight answers to common farm insurance questions.
Farm insurance packages typically combine farm property (dwellings where scheduled, barns, outbuildings), scheduled machinery and equipment, farm liability for operations and premises, and livestock coverage against specified perils where purchased — each subject to causes of loss, limits, deductibles, and endorsements on your policy. Not every farm program covers every item or peril automatically; optional extensions may address equipment breakdown, loss of farm income, or agritourism where available.
Ready when you are
Ready to cover your farm?
Tell us about your buildings, equipment, livestock, and sales activities — we'll compare farm programs and explain what fits.